How Much Should You Put Down? Down Payment Math for First-Time Buyers
"How much do I actually need to put down?" It's the first question almost every first-time buyer I meet asks, and the answer is almost never the scary number they've built up in their head. The math depends on the loan, the price range, and what you want your monthly payment to look like. Here's how to run the numbers on a first home in Gilbert or Eastside Phoenix without the mortgage lender jargon.
Why 20% is the myth that scares people off
Everybody has heard you need 20% down. It's the most repeated piece of real estate folklore I run into, and for most first-time buyers it's simply not true. Plenty of conventional and FHA loans in Arizona accept 3% to 5% down, and VA loans for our military families can go as low as zero down with the right entitlement. The 20% figure matters when you want to avoid private mortgage insurance or when you're trying to keep a monthly payment down, but it is not a gate that keeps you out of the market.
Let me put real numbers on it. In the Gilbert and Eastside Phoenix range I work in, first homes generally run from around $350,000 up toward $500,000. At 5% down, that's $17,500 to $25,000. At 3% down on the low end, it's closer to $10,500. Still real money, but very different from the $70,000 to $100,000 that a 20% figure would demand. Most families can build a realistic path to that far faster than they think.
Run the monthly payment, not just the down payment
Here's the part nobody tells you. The down payment gets all the attention, but it's the monthly payment that actually decides whether you can afford the place. A bigger down payment lowers your monthly payment. A smaller one frees up cash for closing costs, inspections, and the inevitable first-year surprises of homeownership. I always want my buyers to pick the number that leaves them comfortable each month, not the number that looks impressive.
A quick rule of thumb that I keep in my back pocket: for every $10,000 of down payment you add, your monthly payment drops by something in the neighborhood of $60 to $70 depending on the rate. That's the kind of math I put on the table when we're deciding between a couple of similar homes. If an extra $10,000 down knocks $65 off your payment for the life of the loan, that's worth talking about.
Don't forget the money around the down payment
The down payment is not the only number on the board. In Arizona you'll also want to budget for earnest money, a home inspection, an appraisal, title and escrow fees, and your first year of homeowners insurance and property taxes. I'm not going to rattle off a fake closing cost figure, because it varies by price and lender. What I will tell you is this: when we find the place, I walk you through the real estimated costs line by line so there are no surprises at the wire transfer.
So what should you do first?
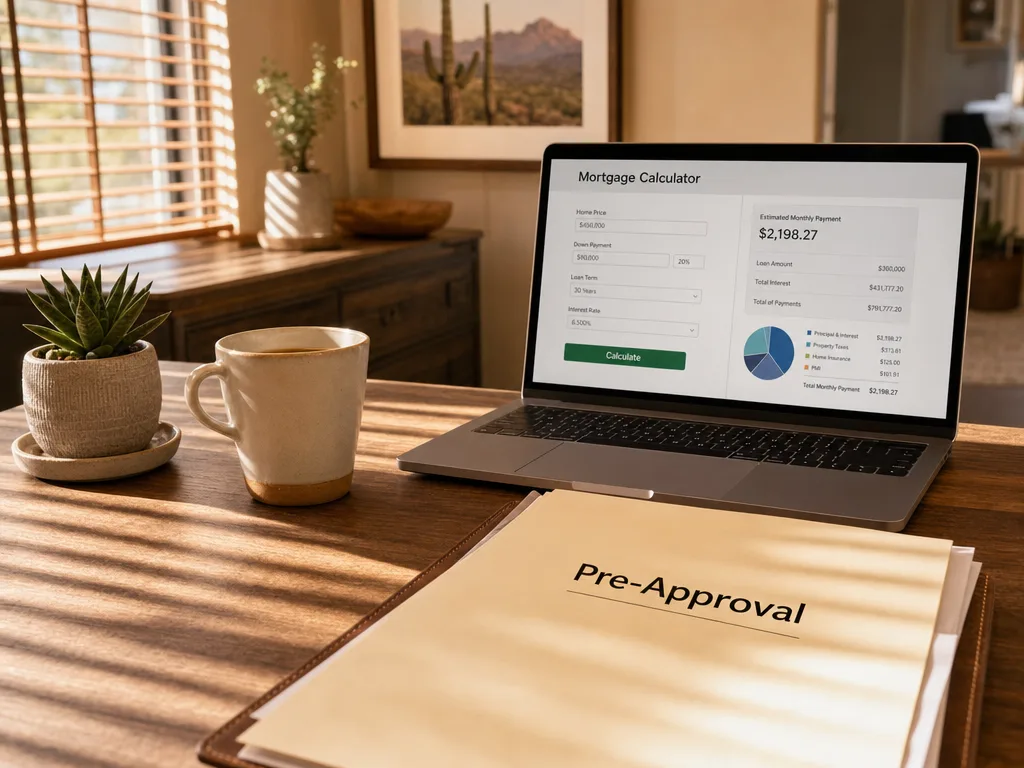
The single best first step is a loan officer who runs your actual numbers, not a generic rule. Get pre-approved and ask them to show you two or three scenarios: one with 5% down, one with 10%, one with 20%. Compare the monthly payments side by side and you'll instantly see what feels right for your budget. Bring that pre-approval to me and we'll shop for homes in the range that fits your real life, not a wish and a prayer.
Buying your first home should feel exciting, not like a pop quiz in a class you never took. That's my job, to clear the fog so you can see the path. Send me a message or schedule a call and we'll run your numbers together, and you can grab my first-time buyer guide while you're at it. Nice talking to you.