Can You Finance a Manufactured Home in Mesa? The 1976 HUD Code Decides
Fourth question in my manufactured-homes series, and the one I get texted more than any other: can you actually get a mortgage on a manufactured home in Mesa? The short answer is yes, when the home was built to the federal HUD Code and sits on land you own. The date that decides it is June 15, 1976. Here is what that date means for your financing, your monthly payment, and your resale, in plain English.
What the 1976 HUD Code actually is
Congress passed the National Manufactured Housing Construction and Safety Standards Act in 1974, and the HUD Code it created took effect on June 15, 1976. From that date forward, every factory-built home had to be constructed to one national standard for safety and quality. Homes built after that date are called manufactured homes. Homes built before it are the old mobile homes, and they are a completely different animal.
Why the date decides your mortgage
When a HUD Code home is affixed to owned land and titled as real property, FHA, VA, and conventional lenders all have programs for it. You can buy it the way you would buy a site-built house: a real mortgage, a real rate, a 15 or 30 year term, and a down payment you already understand. That is the version of this market where the financing door swings wide open.
A pre-1976 home is a different story. Most lenders and insurers will not touch it at all, because it was never built to the federal standard. When you see a cheap mobile home that seems too good to be true, the pre-1976 date is usually why.
The two labels that prove it
Every HUD Code home carries a red certification label on the exterior and a data plate, usually inside a kitchen cabinet or near the electrical panel, that records the builder, the date, and the plant. Lenders and appraisers use those two identifiers to confirm the home is HUD certified, and that confirmation is the gate for financing and insurance. If the label is missing, we can often still verify the home through records, but it slows a deal down. I check for it before we ever write an offer, not after.
What this looks like in the East Valley
Realtor.com currently shows nearly 1,000 manufactured and mobile home listings in Mesa alone, and the same story plays out in Gilbert, Chandler, and Apache Junction. The land-owned, HUD Code, affixed homes are the ones that finance like houses. The personal-property version gets a chattel loan instead, which typically means a higher rate, a shorter term, and a bigger down payment, because the lender's collateral is a movable asset rather than land. Over the life of the loan, that difference can add up to tens of thousands of dollars.
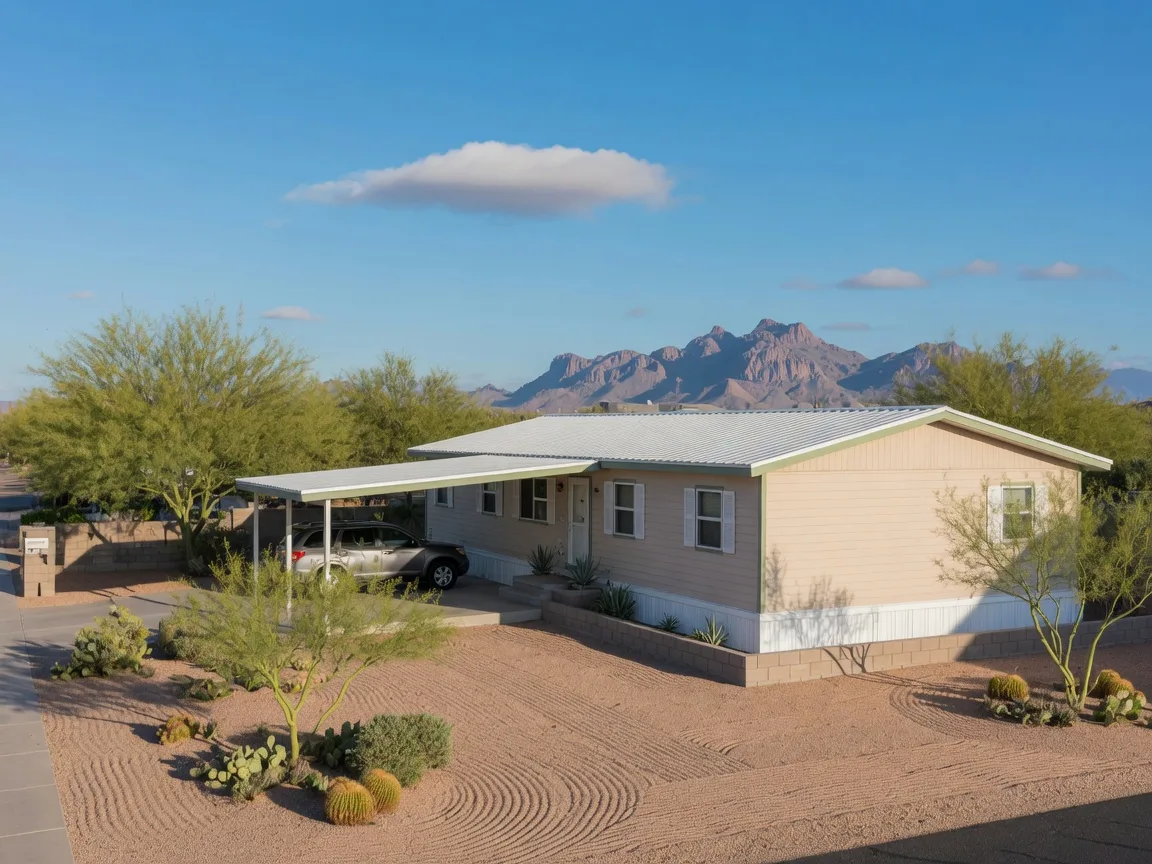
I have personally marketed a substantial owned-land manufactured home here in Mesa, and the HUD date was the first thing we verified. The home was built to code, affixed on a permanent foundation, and titled as real property at the county. It financed, insured, and resold like a house, because it was one. That is exactly the outcome this date stamp makes possible.
This is the fourth deep dive in my manufactured-homes series. Start with the land question in land-owned vs. leased land in Mesa, then the age rules in 55+ vs. non-age-restricted communities, then the affixed vs. non-affixed detail, and the whole picture is in our complete guide to land-owned manufactured homes in the East Valley, which walks through the 1976 HUD Code, financing, HOAs, space fees, titles, insurance, inspections, and resale.
When you are looking at a manufactured home in Mesa and you are not sure whether it can be financed, that is exactly what I am here for. Message me or schedule a call, and I will pull the HUD label, check the title, and tell you straight whether the mortgage door is open. Zero drama, that is my job. Nice talking to you.